Discovering damage to your roof after a storm is a stressful experience that can leave any homeowner feeling overwhelmed. Your roof is the primary shield protecting your largest investment, and when that shield is compromised, the financial implications can be significant. Navigating the world of roof insurance claims often feels like learning a foreign language, filled with terms like 'actual cash value,' 'depreciation,' and 'deductibles.' However, with the right preparation and a clear understanding of the process, you can advocate for your home effectively. This guide is designed to walk you through every step of the journey, from the initial inspection to the final repair, ensuring you have the knowledge to handle your claim with confidence.
Understanding What Your Policy Covers
Before you pick up the phone to call your insurance provider, it is vital to understand the basics of your policy. Most standard homeowners insurance policies cover 'perils,' which are specific events that cause damage. Common covered events include windstorms, hail, fire, and falling objects like tree limbs. However, insurance is not a maintenance plan. Damage caused by neglect, such as failing to clear debris or ignoring long-term wear and tear, is typically excluded from coverage [1].
It is also important to distinguish between Actual Cash Value (ACV) and Replacement Cost Value (RCV). An ACV policy pays out based on the current value of your roof, factoring in depreciation due to age. An RCV policy, conversely, covers the cost to replace the roof with materials of similar quality, regardless of age. Knowing which type of policy you hold will help you manage your financial expectations before the process begins [3].
The Importance of an Independent Roof Inspection
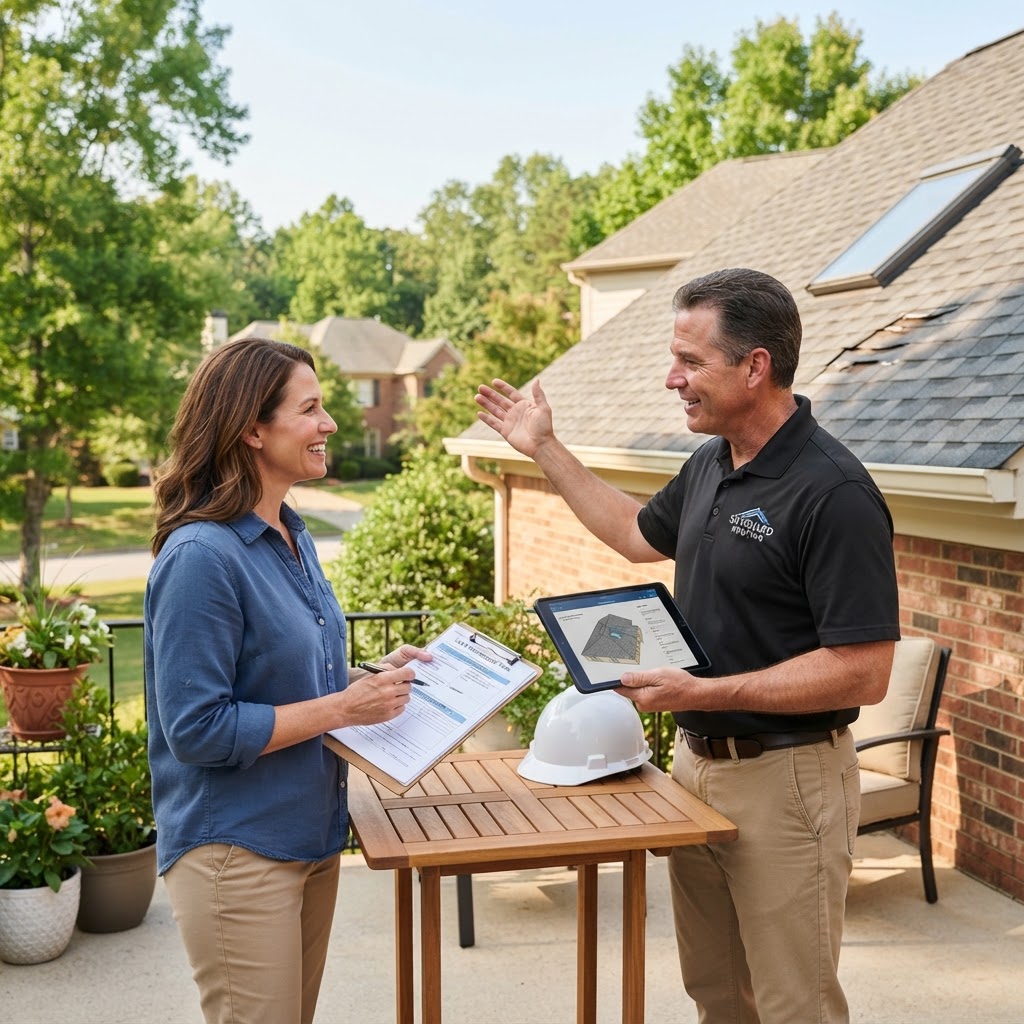
One of the most critical mistakes homeowners make is waiting for the insurance adjuster to arrive before having the roof inspected. You should always seek an independent assessment from a reputable professional first. When you hire a qualified service professional through FIND-A-PRO, you ensure that you have an expert on your side who can identify subtle signs of damage—like hail bruises or wind-lifted shingles—that might be missed by an untrained eye [2].
Pro Tip: Avoid 'storm chasers'—contractors who knock on your door immediately after a weather event promising a free roof. Instead, rely on verified local experts who have a track record in your community. A trusted roofer will document the damage with photos and chalk markings, providing you with a professional estimate that serves as your baseline for the claim [2].
Step-by-Step: Filing Your Claim
Once you have confirmed damage with a professional, the formal process begins. Follow these steps to ensure your claim is handled correctly:
- Document Everything: Take high-resolution photos of the damage from multiple angles. Keep a log of all communications with your insurance company, including names, dates, and claim numbers [6].
- Contact Your Insurer: Notify your provider as soon as possible. Ask them specifically about your filing deadline, as many policies have strict time limits for reporting storm damage [6].
- Prepare for the Adjuster: When the insurance adjuster visits, have your independent inspection report ready. If possible, have your chosen roofing contractor present during the inspection to ensure all damage is accounted for [9].
- Review the Settlement: Once the adjuster submits their report, review the scope of work carefully. If the estimate seems low or misses key damage, you have the right to request a supplement or a re-inspection [4].
Frequently Asked Questions (FAQ)
Q: Should I file a claim for minor damage?
A: If the cost of the repair is close to or less than your deductible, it is often better to pay for the repair out-of-pocket to avoid potential premium increases or a 'claim' on your record.
Q: What if my claim is denied?
A: A denial is not always the final word. You can appeal the decision by providing additional evidence, such as a second opinion from a licensed contractor or a report from a public adjuster [4].
Q: How long does the entire process take?
A: While every case is unique, the typical timeline from the initial report to the completion of repairs ranges from two to six weeks, depending on the severity of the damage and the responsiveness of the parties involved [10].
Key Takeaways
Navigating a roof insurance claim is a marathon, not a sprint. By staying organized, documenting your damage thoroughly, and working with reputable professionals, you can ensure your home is restored to its proper condition. Remember, you don't have to go through this alone. Using a platform like FIND-A-PRO allows you to connect with verified, local roofing experts who can provide the documentation and quality workmanship you need to get your claim approved and your roof repaired. For more tips on maintaining your home's value, check out our <a href="/articles/essential-home-maintenance-guide">essential home maintenance guide</a>. Stay proactive, stay informed, and protect your home for years to come.